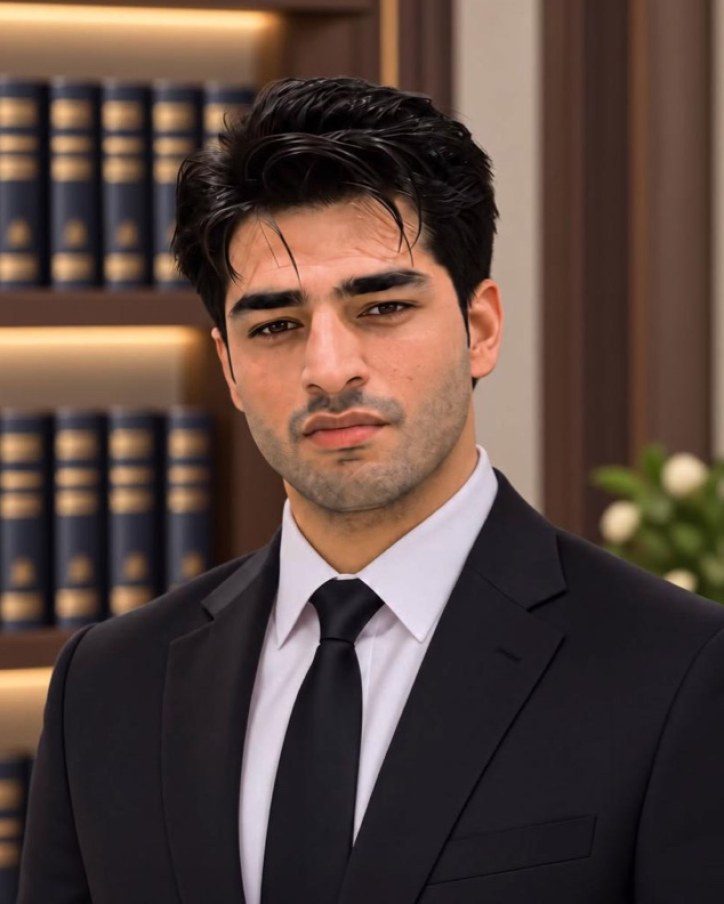
Khalifa Abu Zar
Strategic Regulatory AdvisorRegulatory and Licensing CounselSalahuddin, Saif & Aslam, Attorneys at Law, Lahore
I help fintechs, banks, e-money institutions, payment operators and microfinance banks get licensed in Pakistan, and stay licensed once they are.
I'm a regulatory and licensing counsel in the fintech practice of Salahuddin, Saif & Aslam in Lahore. My work is licence applications and business plans before the SECP, the State Bank and PVARA, and the structuring, contracts and compliance architecture that follow. Most of my clients arrive from elsewhere, instructing from Bahrain, China, Hong Kong, Kenya, Lithuania, Mexico, Nigeria and the Philippines, and need a Pakistani route that works for a product built for another market.
Fintechs, banks, e-money institutions, payment operators and microfinance banks.
SBP, SECP, PVARA, FMU, PSEB.
- Strategic Regulatory AdvisorSalahuddin, Saif & Aslam, Attorneys at Law, Lahore
- Regulatory and Licensing CounselThe fintech practice: licence applications, business plans and the compliance architecture that follows
- LLB (Hons)Liverpool John Moores University
- Certificate in Fintech Strategy and InnovationLahore University of Management Sciences (LUMS)
Practice
Licences I Work On
Around the licence: market entry and perimeter analysis, product structuring for BNPL, nano-lending, wallets and merchant acquiring, AML/CFT and compliance architecture, digital onboarding and electronic contracting, data governance and technology outsourcing.
NBFC Licence
Digital lending, BNPL, nano and SME lending, revolving credit, earned wage access.
- Business plans
- NOC and licence applications
- Policies
- Fit and proper filings
- App whitelisting
EMI Licence
Wallets, e-money issuance, merchant payments.
- In-principle approval applications
- Business plans
- Pilot readiness
- Security and outsourcing frameworks
PSO and PSP Authorisation
Payment gateways, aggregators, switches, merchant acquiring.
- Authorisation filings
- Settlement and acquiring architecture
- Partner agreements
MFB Licence
Microfinance banking.
- Route assessment
- Structuring and the licensing pathway
VASP Licence
Exchanges, custody, stablecoin-linked products.
- Perimeter analysis
- NOC and licence applications
- AML/CFT and Travel Rule readiness
Deal Team
Selected Mandates
Six mandates from the firm's fintech practice on which I'm named in the deal team. Clients are not named.
Pakistan's first digitally integrated revolving credit line
Digital lending in Pakistan had been built around single disbursements. This client wanted a reusable credit line that grows with borrower behaviour, a product with no local precedent. The firm secured the NBFC licensing framework, then architected the legal, regulatory and operational foundations the product needed to exist.
- RegulatorsSECP
- ScopeLicensing, product architecture, electronic contracting, API integrations, digital collections
- My roleOn the deal team
A wallet, acquiring and BNPL ecosystem under one licence stack
Securing the group's NBFC licence and operational launch, then structuring its proposed e-money institution before the State Bank: consumer and merchant wallets, QR payments, gateway infrastructure, merchant acquiring, BNPL and device financing in one mobile-first platform. Most of the work is making two licences from two regulators behave as one product.
- RegulatorsSECP and SBP
- ScopeNBFC licensing, cross-border ownership, EMI business plan, wallet and acquiring architecture, digital onboarding
- My roleOn the deal team
Nano-lending and BNPL, from first structure to licence
Involved from before there was a Pakistani entity: corporate, sponsor and investment structuring, regulatory engagement and the No Objection Certificate process, now continuing into full NBFC licensing and an operable mobile-first lending platform.
- RegulatorsSECP
- ScopeMarket entry, sponsor and investment structuring, NOC process, licensing pathway, BNPL and nano-lending compliance
- My roleOn the deal team
A five-market lending group's route into Pakistan
A lending model built for other markets does not transfer cleanly into Pakistan's perimeter. Market entry and licensing strategy for the group's NBFC platform, alongside assessments of e-money and microfinance bank routes: which combination of licences actually supports the business the group runs elsewhere.
- RegulatorsSECP and SBP
- ScopeMarket entry, NBFC structuring, licensing pathway, EMI and microfinance bank route assessment, operational governance
- My roleOn the deal team
AI credit decisioning inside a licensed lender
Automated underwriting raises questions Pakistan's lending rules were not drafted for: who answers for an algorithmic decline, what a borrower must be told, and how consent to data use is evidenced. Licensing architecture for a proposed NBFC offering nano-loans and BNPL, and the consent, disclosure and governance layer around the credit model.
- RegulatorsSECP
- ScopeLicensing architecture, AI credit decisioning, automated lending workflows, consent and disclosures, data governance
- My roleOn the deal team
Automated consumer finance, built to survive examination
A digital lender for underserved consumers and small businesses, with almost every step of the credit journey automated. Regulatory strategy and the operating architecture beneath it: enforceable electronic contracts, automated decisions that can be explained to a regulator, and data handling that holds up under inspection.
- RegulatorsSECP
- ScopeRegulatory strategy, digital lending architecture, electronic contracting, API integrations, risk and data governance
- My roleOn the deal team
Regulatory Perimeter
Questions I’m Working On
Can a global exchange serve Pakistani users without a local licence?
Virtual Assets Act 2026; Pakistan Virtual Asset Services Regulations 2026
The answer turns on conduct rather than incorporation. Targeting, language, app-store presence, marketing and access to local payment rails decide whether a platform is carrying on business here.
When does stablecoin settlement become a regulated payment?
Foreign Exchange Regulation Act 1947; PSO/PSP Rules 2014; EMI Regulations 2019
Routing may be able to sit offshore; collection and payout in Pakistan need a licensed bank, EMI or payment operator. Because the Virtual Assets Act does not override the Foreign Exchange Regulation Act, any flow that converts rupees is a foreign exchange question first.
Can a platform hold a wallet without becoming an e-money institution?
Payment Systems and Electronic Fund Transfers Act 2007; EMI Regulations 2019
A closed-loop balance holding customer funds sits close to the definition of e-money. Staying outside it means onboarding, collection, settlement and payout all stay with a licensed provider, and stay there through the next product release.
Where does a technology intermediary end and a lender begin?
NBFC and Notified Entities Regulations 2008; SECP Circulars 12 and 14 of 2024
The distinction has to hold in the product as well as the contract: whose name the borrower sees, who sets the terms, where the money sits, and what the disclosures say.
Can outbound payments stay outside the payments perimeter?
Foreign Exchange Regulation Act 1947; State Bank Foreign Exchange Manual
Rupees collected locally and remitted abroad through a licensed bank raise foreign exchange questions before payment-systems ones, and the order in which the two regimes apply usually decides whether the model works at all.
Is a token a virtual asset or a security?
Virtual Assets Act 2026; Securities Act 2015
The 2026 regulations create licence categories for fiat- and asset-referenced token issuance, while securities law remains the SECP's. Which regime applies depends on what the token represents and what its holders are promised.
Contact
Speak With Khalifa
Bringing a financial product to Pakistan? Write to me about licensing, market entry or regulatory structuring.
- DegreeLLB (Hons), Liverpool John Moores University
- CertificateCertificate in Fintech Strategy and Innovation, Lahore University of Management Sciences (LUMS)
- RegulatorsSBP, SECP, PVARA, FMU, PSEB
Client identities are withheld. Nothing on this page is legal advice.