Digital Ecosystems And Financial Licensing Experts
A Fintech Powerhouse.
SSA advises FinTechs, Financial Institutions, Digital Asset Businesses and Payment Companies on licensing, market entry and cross-border transactions from SBP, SECP, SIFC and PVARA regimes to international financial regulators FCA, SEC, VARA and MiCA.

Salahuddin, Saif & Aslam
Attorneys at Law
Licensing · Structuring · Compliance
$1B+
Transactions closed
20+ yrs
Years of combined regulatory and fintech experience
100+
Licensing applications; NBFCs, EMIs, PSOs, PSPs, Virtual Asset Service Providers, and real-world blockchain projects
500+
Active ecosystems supported
Recognition

The ranking reflects a practice that is cross-border by nature. Our team advises clients operating across Asia, the Middle East, Europe, Africa and the Americas, while remaining rooted in Pakistan's regulatory environment.
Industry Leadership
Advisor and Member, Pakistan FinTech Association
Pakistan's largest FinTech Industry Association.
Global Recognition
Exclusive Leading Expert (Pakistan Section), The Global Legal Post 2027
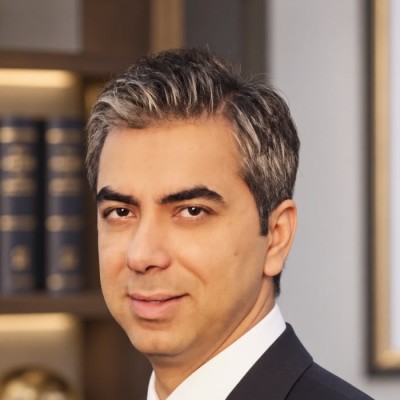
Founder & Managing Partner
Hassaan Salahuddin
Band 1 · FinTech · Chambers Asia‑PacificFintech Regulation, Financial Licensing, Digital Assets and Cross-Border Structuring. Lead counsel on the firm's principal fintech mandates, including pioneering EMI, P2P Lending, Digital Lending, VASP Licensing and Financial-Services Regulatory Matters.
e-portfolio (opens in a new tab)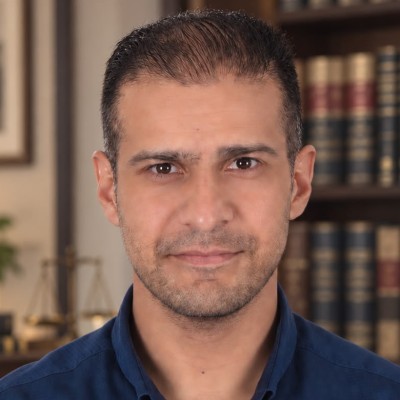
Junior Partner
Taha Hafeez
Band 2 · FinTech · Chambers Asia‑PacificAdvises fintech and financial-services clients on SECP and SBP Regulatory Approvals, Compliance Frameworks and Commercial Agreements.
e-portfolio (opens in a new tab)The Work Behind the Positioning.
Track Record
-
Trusted counsel for global exchanges, digital infrastructure providers and digital asset platforms under PVARA's 10-category licensing regimes under the Virtual Assets Act 2026.
-
Leading advisor to the largest number of lending non-banking finance company mandates in Pakistan.
-
Built the legal architecture for the application layer of Pakistan's first SECP approved digital revolving credit line product.
-
Secured Pakistan's inaugural Peer-to-Peer (P2P) lending licence.
-
Pioneers of the electronic money institution licence in Pakistan.
-
Legal architects currently leading the application layer for a Greenfield Digital Microfinance Bank.
Selected Mandates
12 recent mandates across payments, lending, virtual assets and cross‑border structuring.
Policy
We Are in the Room Before the Rules Are Written.
Regulatory positioning holds up better when you were part of the conversation that produced the regime.
-
Active involvement in the policy discussion as Pakistan's virtual asset regulator rolls out the Virtual Assets Act 2026.
-
Ongoing engagement in the policy conversation around Pakistan's evolving nano-lending regulatory framework.
-
Active adviser on State Bank of Pakistan greenfield microfinance bank licensing projects.
-
Structured Pakistan's largest Digital Financial Wellness Initiative.
Chambers Asia-Pacific · FinTech Legal
Top Ranked · 2024 to 2026
What truly distinguishes them is their ability to combine legal precision with commercial pragmatism — delivering advice that is not only technically sound but also actionable in the real world.
SSA's deep sector knowledge and commercially aligned approach have helped ensure that our legal and regulatory operational frameworks are structurally sound, minimally risky and scalable.
What sets him apart from peers is his ability to handle complex regulatory and contractual issues without overcomplicating them. He brings clarity and structure to fast-moving, high-stakes projects.
Hassaan's proactive approach, deep familiarity with regulatory frameworks, and ability to communicate effectively with regulators makes him an invaluable partner in high-value and sensitive matters.
Taha brings a calm, solutions-oriented mindset to every engagement and is always well prepared and thoughtful in his recommendations.
Hassaan Salahuddin is the firm's managing partner and its lead lawyer on FinTech matters and projects. He wins praise for his strong client service in transactional matters and for his advice on financial regulatory issues.
Hassaan Salahuddin ensures that he finds workable solutions to complex matters, and he is clear and firm on his advice.
01 / 07
Core Services
Where We're Most Often Engaged.
From virtual asset licensing to ongoing compliance, the work mostly falls into seven areas.
Licensing with the Pakistan Virtual Assets Regulatory Authority (PVARA) under the Virtual Assets Act 2026, covering exchanges, custodians, and token issuers. A licence is the starting point, not the finish line, so we stay on for the AML, reserve disclosure, and cybersecurity obligations that keep it standing up to scrutiny.
Who We Serve
Regulator
Pathway
NOC / Sandbox Incorporation Licence Operations
Cryptocurrency and token structuring, smart contract review, DeFi and Web3 legal frameworks, NFT and digital asset transactions, and blockchain-based financial infrastructure. Cross-border blockchain venture structuring and AML/CFT compliance for virtual assets sit with the same team.
Who We Serve
Regulator
Pathway
Entity & Token Structuring Perimeter Assessment Documentation PVARA Interface
SBP authorisation for payment and e-money institutions, from application strategy and capital structuring through regulator engagement and final approval, with senior lawyers directly involved throughout.
Who We Serve
Regulator
Pathway
Regulatory Route Application Package In-Principle Approval Pilot Operations Commercial Operations
Regulatory positioning for Nano-Lending, SME finance, Earned Wage Access, and BNPL, the same product categories the firm has helped bring to market in Pakistan before.
Who We Serve
Regulator
Pathway
Activity Structuring NOC NBFC Licence Regulatory Observations Launch
AML/CFT frameworks built to survive an audit, the ongoing reporting obligations that come with a licence, and the regulator correspondence when questions get asked, rather than stepping in only after something's gone wrong.
Who We Serve
Regulator
Pathway
Framework Design Policies & Controls Reporting Inspections Remediation
Entity and transaction structures for businesses operating across Pakistani and foreign jurisdictions, worked through against the practical realities of exchange controls, tax residency, and cross-border money movement, not just how the structure looks on paper.
Who We Serve
Regulator
Pathway
Entity Structuring Foreign Investment Authorised Dealer Process Repatriation
Term sheets, investor documentation, and negotiation support on funding rounds for fintech companies, bridging founding teams with institutional money coming in from China, the Middle East, and the US.
Who We Serve
Regulator
Pathway
Term Sheet Structuring Documentation Closing Post-Investment Governance
Where We Work
Active Across Twenty‑One Jurisdictions.
Every mandate is anchored in Pakistan, with the regulators, partners and capital on the other side of the border.
Insights
Latest Updates
Regulatory developments as they happen, written for the businesses they affect.
August 2026
Virtual Assets Act 2026: what fintech businesses need to know
PVARA licensing is open. What compliance looks like for existing and new operators.
July 2026
Structuring cross-border blockchain ventures
How founders are structuring entities across Pakistani and international jurisdictions.
June 2026
New SECP fintech guidelines, explained
A breakdown of recent guidance and its practical impact on licensed operators.
How We Work
From Market Entry to Long‑Term Legal Partnership.
We support fintechs and financial businesses throughout their lifecycle, combining commercial advice, regulatory expertise and dispute resolution under one roof.
01 / 04
Next: Retainer & Commercial Advisory
Turnkey Solutions
Market entry and licensing
SSA takes a business from the decision to enter Pakistan to a licensed, operating company. We decide which licence the product needs, structure who owns and controls it, and run the application through every approval stage.
SECP
SBP
PVARA
Scope of the Mandate
- Perimeter and Route
- Sponsors and Structure
- The Application Case
- Approval Stages
02 / 04
Next: Integration
Retainer & Commercial Advisory
Continuing and standalone counsel
SSA acts as outside counsel to licensed fintech businesses once the licence is granted. We keep you informed of regulatory change, build and maintain your compliance framework, and handle the contracts and decisions that arise as the business runs.
What the Retainer Covers
- Regulatory Updates
- Compliance Framework
- Contracts & Negotiation
- Product Expansion
- Ownership & Corporate Matters
- Workforce Management
03 / 04
Next: Regulatory Compliance & Supervision
Integration
Banks, payment rails, APIs and cross-platform integration partnerships
SSA puts a licensed business’s financial and technology infrastructure into operation: the banks, payment networks and technology providers it depends on, and the contracts between them, from planning through deployment.
The Ecosystem Around a Licence
- Technology Partners
- Payment Gateway Solutions
- Telecom & AI Aggregation
- Cross Platform Integrations
- Operational Readiness
- Cross Border Architecture
04 / 04
Next: Financial Crime, AML & Enforcement Proceedings
Regulatory Compliance & Supervision
Post-licence support and compliance
SSA keeps licensed businesses in good standing with their regulators. That means dealing with the regulator directly, getting approvals before changes take effect, and running the continuing obligations of the licence.
SECP
SBP
PVARA
Going Live Under the Licence
- Commencement Readiness
- Go Live Plan
- Compliance Reporting
- Regulatory Change Adoption
- Customer Disclosures
- Regulatory Audit
Any Stage
Back to: Turnkey Solutions
Financial Crime, AML & Enforcement Proceedings
Available at any stage, or independently
SSA represents financial businesses in financial crime and anti-money laundering investigations, regulatory enforcement, cybercrime proceedings and the disputes that follow. It can be engaged at any stage, or independently.
Types of Matter
- Regulatory Enforcement
- Financial Crime and AML Investigations
- Cybercrime Proceedings
- Fintech and Commercial Disputes
- Early Advice on Exposure
01 Can a global exchange serve Pakistani users without a local licence? PVARA
It depends on whether it carries on business in or from Pakistan, in which case the Virtual Assets Act requires a Pakistani company holding a PVARA licence. Where the exchange is incorporated does not decide this. Targeting, soliciting or onboarding people here, through marketing, payment rails or rupee pricing, does. PVARA offers an NOC route to licensing and a sandbox for new products.
VASP & Digital Assets02 When does stablecoin settlement become a regulated payment? PVARA SBP
When virtual assets are transferred or settled for customers, which is its own PVARA licence category wherever the routing sits. The rupee leg is a separate State Bank matter. Collection and payout run through banks and SBP-authorised providers, and any rupee conversion is also governed by Pakistan’s Foreign Exchange Act, which the Virtual Assets Act does not override.
Payments & EMI Licensing03 Can a platform hold a wallet without becoming an e-money institution? PVARA
Yes, if the balance is not e-money, meaning stored value issued against funds and accepted as payment by parties other than the issuer. A balance usable only on the platform generally falls outside that. One that can be sent to other users or spent elsewhere does not. A wallet holding virtual assets is custody, a separate PVARA category.
Payments & EMI Licensing04 Where does a technology intermediary end and a lender begin? SECP
Where the platform starts acting as the lender. Lending is for a licensed NBFC, and SECP’s rules require the NBFC’s name and licensing status on the app and a Key Fact Statement before disbursement. The test is applied to the product: whose name the borrower sees and whose terms apply, rather than what the contract says.
Lending & NBFC Licensing05 Can outbound payments stay outside the payments perimeter? PVARA
Foreign exchange comes first. Sending rupees abroad runs through authorised dealers, whatever the technology. Pakistan’s Foreign Exchange Act applies alongside the Virtual Assets Act, so foreign exchange approvals are separate from PVARA licensing. Whether a payment-systems licence is also needed depends on who collects and pays out the rupees.
Cross-Border Structuring06 Is a token a virtual asset or a security? PVARA SECP SBP
It depends on what the token is and what it gives the holder. The Virtual Assets Act excludes securities within SECP’s jurisdiction, but its definition of a virtual asset appears to reach regulated assets issued on blockchain. PVARA classifies by substance and consults SECP or SBP where needed, so a token with investment-type rights should be assessed under both regimes.
Blockchain, Web3 & Token StructuringTell Us What You're Building.
Tell us briefly what you're dealing with. A senior member of the team reads every enquiry and responds within one business day.
WeChat 微信
Scan to add, or copy the ID
Press and hold the QR to save it, then in WeChat: Scan › Album

wxid_nqzxfol7x2mv12

wxid_ozy2wfuydrzc12